Credit & Scoring
A borrower’s score decides the price of the loan, and the rules for producing that score are in the middle of a rewrite. This section covers the scoring models mortgage lenders are allowed to use, what rapid rescoring can and cannot do, and how tradelines, inquiries and disputes read on a mortgage credit report. It is written for the person who has to explain the number to the borrower.
5 posts, newest first
 Tracker
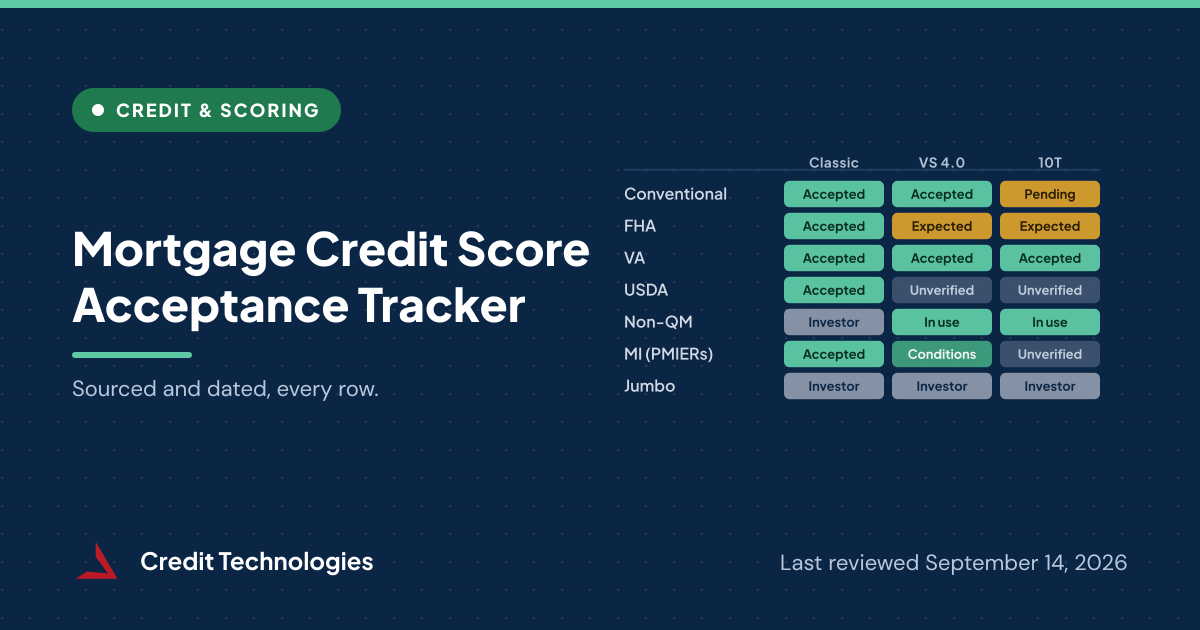
What Credit Score Do Mortgage Lenders Use? Accepted Models and Report Requirements, Updated September 2026
Mortgage lenders use one of three approved score models: Classic FICO, VantageScore 4.0, or FICO Score 10T. This tracker states what each loan program accepts today, with a source and an as-of date on every row.
 Guide
Rapid Rescoring vs. Credit Repair vs. Debt Settlement: What Actually Moves a Mortgage Approval
Rapid rescoring, credit repair, and debt settlement sound similar and work nothing alike. What each one does to a credit report, who pays, how long it takes, and what it means for a mortgage approval. From the company that invented rescoring in 1997.
 Guide
What Is a Tradeline? A Mortgage Lender's Guide
A tradeline is any account on a credit report, from a credit card to a mortgage. This guide covers what tradelines contain, how they drive FICO and VantageScore results, why their impact is often counter-intuitive, and why accurate tradeline data is the foundation of any score improvement.
 Guide
What Is a Rapid Rescore? A Guide for Mortgage Lenders
A rapid rescore updates corrected or outdated credit data in days, lifting a borderline FICO score and clearing conditions that stall an approval. Here is how rescoring works and why one rescore is often a built-in pricing advantage.
 Update
The New Center: How Smart Lenders Are Navigating the 2026 Credit & Market Shakeup
Rising credit costs, scoring model upheaval, trigger lead restrictions, and a fragile housing market are converging in 2026. Here is how lenders can find stable ground.


